Vladislav Zaimov is a heavyweight in the telecom arena, having spent decades dissecting the complex risks associated with vulnerable networks and the infrastructure of enterprise communications. As the industry watches SpaceX maneuver from the stars down to the terrestrial soil, Zaimov’s insights provide a critical map for understanding how spectrum acquisition defines power in 2026. This conversation explores the strategic pivot toward 600MHz assets, the high-stakes deadlines facing unbuilt licenses, and the shifting leverage in negotiations with established mobile giants. We delve into the technical necessity of low-band airwaves for indoor coverage and the logistical hurdles of building a nationwide network from the ground up while navigating existing lease agreements.
SpaceX has recently targeted 800MHz assets to transition toward becoming a major mobile carrier. How does acquiring additional 600MHz spectrum from entities like Comcast or Bluewater specifically solve terrestrial coverage gaps, and what technical advantages does low-band spectrum provide for penetrating buildings?
Low-band spectrum, particularly in the 600MHz range, acts as the bedrock for any carrier hoping to provide a seamless user experience because of its incredible propagation characteristics. Unlike higher frequencies that struggle with physical obstacles, 600MHz waves can travel long distances across rural plains and, more importantly, slice through the thick concrete and steel of modern skyscrapers. For a company like SpaceX that is already moving into 800MHz assets, adding 600MHz provides a necessary layer of “indoor-out” reliability that satellite signals alone often struggle to maintain in dense urban environments. Without this terrestrial anchor, a mobile user might lose a call the moment they step into an elevator or a basement cafe. By securing these assets, a carrier can effectively fill the “dead zones” that exist outside of traditional satellite reach, creating a network that feels robust and omnipresent to the end consumer.
T-Mobile currently leases much of the available 600MHz spectrum with options to buy through 2028. If a new player enters this space, how do they navigate lease-termination notices and the resulting transition periods, and what does this timeline mean for immediate network deployment?
Navigating the 600MHz landscape is like walking through a legal minefield because of the existing encumbrances held by T-Mobile. Even if an entity like SpaceX reaches a deal with Comcast, they wouldn’t walk away with “clean” spectrum right away; they would inherit a waiting game that stretches toward the 54-month mark of the lease, around April 2028. There is an outside date of April 12, 2029, which means any immediate dreams of flipping a switch on a new nationwide network are tempered by these hard contractual realities. A newcomer has to be patient, using this multi-year transition period to finalize their hardware stack and site acquisition strategy while T-Mobile eventually clears the deck. It is a slow-burn strategy where you are essentially buying a future seat at the table rather than an immediate entry into the market.
Bluewater Wireless holds 66 unbuilt licenses facing a strict July 2028 FCC deadline. What are the logistical risks of acquiring “unbuilt” spectrum, and how can a company accelerate infrastructure development to meet regulatory mandates while ensuring deep coverage in markets like Houston and Atlanta?
Acquiring unbuilt licenses is a high-stakes race against the clock because the FCC has no patience for “spectrum squatting.” With 66 licenses sitting idle and a hard deadline of July 3, 2028, any buyer has to hit the ground running with an aggressive deployment schedule that involves rapid tower co-locations and hardware installation. In major hubs like Houston and Atlanta, where SpaceX could see significant depth, the logistical challenge involves coordinating thousands of individual site upgrades simultaneously to prove “substantial service” to regulators. If they fail to meet those build-out requirements, those expensive licenses could be revoked, meaning the company must have their supply chain and labor force ready to move the moment the ink is dry. It’s a stressful, capital-intensive sprint that requires a perfect alignment of regulatory compliance and engineering boots-on-the-ground.
Owning physical spectrum can be used as a bargaining chip in mobile virtual network operator (MVNO) negotiations. How does a terrestrial spectrum portfolio change the power dynamic with established giants like AT&T or Verizon, and what specific wholesale advantages does this provide to a satellite-first company?
In the world of telecom, spectrum is the ultimate currency, and owning your own airwaves completely flips the script when sitting across from giants like AT&T or Verizon. When a company owns a terrestrial portfolio, they are no longer just a “renter” or a humble MVNO petitioner; they become a peer that can offer reciprocal roaming or spectrum swaps. This “signaling device” tells the incumbents that if they don’t offer favorable wholesale rates, the newcomer has the physical capacity to build a competing network and take those customers away entirely. It provides a massive safety net in negotiations, allowing a satellite-first company to demand better margins because they have a credible “Plan B” to fall back on.
Strategic analysts suggest that terrestrial expansion could serve as a “bolt-on” to satellite ambitions or as a signaling device for the industry. In what ways does a hybrid satellite-terrestrial network improve service reliability for mobile users, and what are the step-by-step challenges of integrating these two distinct technologies?
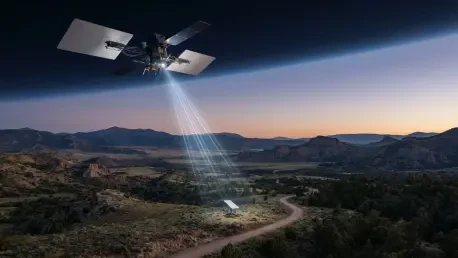
The beauty of a hybrid network is that it eliminates the “unreachable” tag for any mobile device, combining the broad, overhead reach of Starlink with the deep, localized power of 600MHz towers. For the user, this means their phone might use a terrestrial tower in downtown Detroit or Denver for high-speed data, but seamlessly switch to a satellite link the moment they drive into a remote canyon where towers don’t exist. The integration challenge is immense, requiring a unified core network that can manage handoffs between a satellite moving at 17,000 miles per hour and a stationary ground station without dropping a packet. You have to solve for latency differences, varying signal strengths, and the hardware complexity of making a standard smartphone talk to two very different types of infrastructure simultaneously.
What is your forecast for SpaceX’s expansion into the terrestrial mobile market?
I expect SpaceX to continue its calculated “land grab” of low-band spectrum as a dual-purpose strategy to ensure they aren’t boxed out by the big three carriers. Within the next few years, we will likely see them use these assets more as a powerful bargaining tool to secure a favorable, long-term MVNO deal rather than attempting to build 50,000 towers overnight. However, by the time we hit those 2028 and 2029 deadlines, if the wholesale market remains too restrictive, don’t be surprised if they pivot to a full-scale terrestrial rollout in high-value markets to complement their global satellite dominance. They are playing a long game where the goal is to be the only provider on Earth that can truly claim 100% coverage, regardless of whether you are in a skyscraper or the middle of the ocean.