The transition to a fully digital communication framework is expected to see a massive $158 billion influx of value specifically in SIP trunking and IP PBX. As legacy copper-based telephone lines continue their inevitable decline, Voice over Internet Protocol has emerged as the foundational architecture for both enterprise and consumer interaction. Current industry projections indicate that the global market will achieve a valuation of approximately $305.11 billion by 2030, sustained by a robust compound annual growth rate of 16 percent. This shift is not merely a technical upgrade but a fundamental restructuring of the global telecommunications landscape, which is estimated to reach nearly $4 trillion within the same timeframe. Within the even broader context of the information technology industry, internet-based voice services now represent a significant portion of the digital economy, moving from a specialized niche to a universal standard for connectivity. The acceleration of cloud-integrated services and the increasing demand for high-definition communication platforms have created a environment where voice data is no longer a standalone service but a primary component of a unified digital experience.
Regional Dominance: The North American Economic Engine
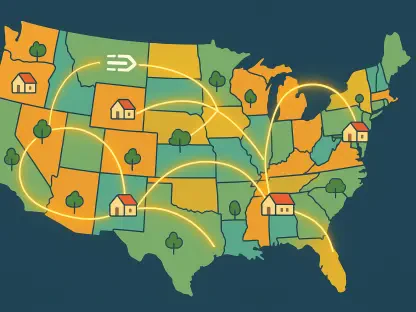
North America continues to hold its position as the primary driver of innovation and market value within the telecommunications sector. From 2026 to 2030, the regional market is expected to experience a period of intense growth, with valuations rising from approximately $52 billion to over $109 billion. This dominance is largely supported by a highly mature broadband infrastructure and the widespread deployment of 5G networks, which provide the low-latency environments necessary for professional-grade voice and video transmission. In the United States, specifically, the market is anticipated to expand to $94 billion by the end of the decade, as corporate entities and government agencies aggressively move away from traditional Public Switched Telephone Networks. The sheer scale of the American market is fueled by a unique convergence of technical readiness and high enterprise demand, ensuring that the region remains the global benchmark for service standards and deployment strategies. As companies prioritize digital resilience, the investment in local data centers and cloud nodes across the continent has further solidified North America as the epicentral hub for global voice traffic management.
Beyond the general infrastructure, specific industry sectors within the United States are accelerating the adoption of specialized VoIP applications. The healthcare, finance, and education sectors are leading this charge, as these industries require communication frameworks that are not only scalable but also strictly compliant with security regulations. In healthcare, for example, the integration of secure voice services within telehealth platforms has become a mandatory operational standard, while financial institutions utilize high-fidelity voice data for precise record-keeping and customer authentication. This demand for secure, high-quality connections has prompted service providers to develop dedicated private branch exchanges and trunking solutions tailored to the unique regulatory requirements of the American market. The presence of major technology hubs and a culture of early adoption among small-to-medium enterprises have also contributed to a competitive environment where service quality and feature innovation are constantly pushed to new limits. Consequently, the North American market serves as a vital testing ground for new functionalities before they are scaled to global audiences.
Technological Foundations: SIP Trunking and Cloud-Based Exchange
Session Initiation Protocol trunking is projected to emerge as the most significant segment of the market, potentially capturing nearly 48 percent of the total global share by 2030. This specific technology allows businesses to consolidate their voice and data traffic onto a single internet connection, effectively replacing traditional circuits with a more flexible and cost-effective digital alternative. For multinational corporations, the shift to this method offers a strategic advantage by providing a unified communication backbone that can be managed from a central location, regardless of the number of international offices involved. The projected value of this segment alone is expected to reach $147 billion, driven by the increasing obsolescence of legacy hardware and the growing need for network redundancy. As organizations seek to improve their disaster recovery protocols, the ability of internet-based trunking to reroute traffic instantly in the event of a localized outage has made it an essential component of modern business continuity planning. The simplicity of scaling these connections—adding or removing capacity as needed—contrasts sharply with the rigid and expensive requirements of traditional telephony.
In conjunction with advanced trunking solutions, the evolution of Private Branch Exchange systems toward hosted and managed cloud environments is redefining corporate internal communications. Hosted IP systems are rapidly gaining traction as companies look to eliminate the significant capital expenditures and ongoing maintenance labor associated with on-premise hardware. By utilizing these cloud-based solutions, organizations can provide their employees with enterprise-grade features such as intelligent call forwarding, sophisticated auto-attendants, and integrated voicemail-to-email services, all accessible through a variety of devices. This transition to hosted platforms allows even small businesses to project a professional image and access tools that were previously reserved for large corporations with massive IT budgets. Furthermore, the integration of these systems with other enterprise software, such as customer relationship management tools, enables a more holistic view of client interactions. The move toward cloud-native communication ensures that the system is always updated with the latest security patches and features without requiring manual intervention from the end-user, thereby significantly reducing the risk of technical debt and security vulnerabilities.
Economic Catalysts: Efficiency and the Decentralized Workforce
One of the most persistent drivers of the 16 percent annual growth rate is the undeniable economic efficiency offered by internet-based communication platforms. By bypassing the physical infrastructure of traditional telephone carriers and avoiding the associated long-distance and international roaming charges, businesses are able to realize substantial savings on their monthly operational expenses. Estimates suggest that this cost-effectiveness contributes approximately 2.2 percent to the market’s annual expansion, as companies redirect their saved capital toward other areas of digital transformation. The ability to manage voice, video, and messaging through a single service provider also simplifies administrative tasks, reducing the number of contracts and billing cycles that an organization must monitor. For startups and smaller firms, the low barrier to entry provided by subscription-based models means they can establish sophisticated communication networks with virtually no upfront hardware investment. This democratization of professional communication tools has leveled the playing field, allowing organizations of all sizes to compete effectively on a global scale while maintaining lean operating budgets.
The profound shift toward remote and hybrid work models has transformed VoIP from a beneficial option into an absolute necessity for the modern organization. With teams often distributed across multiple time zones and locations, the need for a communication system that is device-agnostic has never been greater. Modern platforms allow employees to transition seamlessly between their desktop applications, smartphones, and specialized handsets, ensuring that they remain connected to the corporate network wherever they have an internet connection. This flexibility is expected to add roughly 2.0 percent to the industry’s yearly growth as firms continue to invest in tools that support a decentralized workforce. Features such as real-time file sharing, screen sharing, and high-definition video conferencing are now standard components of these platforms, enabling collaboration that rivals in-person interaction. As the competition for global talent intensifies, providing employees with reliable and flexible communication tools has become a key factor in recruitment and retention strategies. The ability to maintain a consistent professional presence regardless of physical location is now a core requirement for any business operating in the contemporary economy.
Next-Generation Infrastructure: 5G and Artificial Intelligence
The continued global rollout of high-speed 5G networks is providing the technical stability required to support the next generation of voice services. With its significantly higher bandwidth and lower latency compared to previous cellular generations, 5G ensures that internet-based calls maintain high fidelity even when users are moving through high-traffic urban areas. This improvement in connectivity is a critical enabler for the widespread adoption of mobile applications, effectively removing the last remaining advantages held by traditional landline and legacy mobile systems. In historically underserved regions, the deployment of 5G and satellite-based internet services is allowing communities to skip the era of copper wiring entirely and move directly to a digital communication framework. This infrastructure improvement is estimated to contribute about 1.8 percent to the overall market expansion, as it opens up new demographics and geographical areas to service providers. The reliability of these networks also supports more data-heavy applications, such as immersive video conferencing and augmented reality collaboration, which are becoming increasingly integrated into the standard communication suite.
Artificial Intelligence has moved from being a experimental add-on to a central pillar of innovation within the communication sector. Leading service providers are now integrating AI-driven speech analytics into their platforms to provide real-time insights into customer interactions, allowing businesses to monitor sentiment and improve service quality on the fly. Automated transcription services have also become highly sophisticated, converting voice data into searchable, structured text for better record-keeping and legal compliance. Furthermore, intelligent routing systems use machine learning algorithms to direct incoming calls to the most appropriate agent or department based on the caller’s history and the context of their inquiry, significantly reducing wait times and improving resolution rates. These AI-enhanced features offer a level of value that goes far beyond simple audio transmission, turning every phone call into a source of actionable data. As these technologies mature, the integration of natural language processing will enable even more advanced interactions, such as real-time language translation during live calls, further breaking down the barriers to global business and personal communication.
The Competitive Landscape: Market Fragmentation and Integration
The global market for internet-based voice services is characterized by a high degree of fragmentation, which fosters a climate of intense competition and rapid technological evolution. Despite the massive financial scale of the industry, the top ten largest providers currently account for only about 6 percent of total global revenue, leaving 94 percent of the market to a diverse array of regional specialists and niche service providers. This landscape offers significant opportunities for smaller companies to gain ground by offering specialized services or catering to specific vertical markets that require unique configurations. Microsoft currently holds a leading position with a 1 percent share of global sales, a status largely attributed to the deep integration of its voice capabilities within its broader ecosystem of productivity and collaboration tools. Other major players include massive telecommunications firms like AT&T, Verizon, and Deutsche Telekom, as well as technology giants like Alphabet and Cisco. These organizations maintain their competitive edge by investing heavily in global network infrastructure and forming strategic partnerships that allow them to offer comprehensive, all-in-one communication packages to enterprise clients.
The vast ecosystem of this industry involves a complex value chain that spans from hardware manufacturers to service distributors and end-users. Technology suppliers provide the foundational hardware and the software protocols that make internet communication possible, while large-scale distributors like Ingram Micro and Tech Data facilitate the logistics of getting these tools into the hands of service providers and businesses. At the end of this chain are the users, ranging from individual consumers using mobile apps to multinational corporations requiring multi-layered, secure networks. The current period is seeing a significant amount of capital being injected into the development of new cloud-native private branch exchanges, such as those recently launched to lower operating costs and improve the user experience. These innovations focus on creating smoother integrations with third-party software, such as enterprise resource planning and accounting tools, allowing for a more streamlined workflow. As the market approaches its $305 billion target, the successful companies will be those that can effectively navigate the complexities of global regulations while meeting the increasing demand for secure, high-fidelity, and data-rich communication platforms.
Future Strategic Outlook: Value Chains and Long-Term Implementation
The evolution of the global communication landscape reached a definitive milestone as organizations worldwide completed their departure from legacy systems. Businesses that recognized the strategic importance of this shift early on were able to implement robust digital frameworks that utilized the projected $158 billion growth in trunking and exchange sectors. These leaders focused on creating agile environments where voice services acted as an intelligent bridge between various departments and global regions. The integration of high-speed 5G networks proved to be the final piece of the puzzle, providing the necessary stability for mobile applications to perform with the same reliability as traditional fixed lines. For many enterprises, the successful deployment of these systems involved a comprehensive audit of existing infrastructure and a clear roadmap for phasing out obsolete hardware in favor of cloud-native solutions. This proactive approach allowed firms to minimize technical debt while gaining access to advanced features like AI-driven analytics and automated compliance tools. The transition period demonstrated that the most effective communication strategies were those that prioritized scalability and security, ensuring that the network could grow in tandem with the organization’s global ambitions.
Moving forward, the primary focus for stakeholders shifted toward the optimization of data security and the further refinement of artificial intelligence within the communication suite. Organizations realized that as voice data became increasingly integrated with other business applications, the protection of this data became as critical as securing financial records. Implementation strategies began to incorporate end-to-end encryption and multi-factor authentication as standard requirements for all communication nodes. Furthermore, the adoption of intelligent routing and real-time transcription tools allowed businesses to extract much more value from their daily interactions, turning simple conversations into a structured database of customer insights and operational knowledge. The industry moved beyond the simple replacement of telephones to the creation of a unified, intelligent platform for human and machine interaction. For those looking to capitalize on this $305 billion market, the priority became the constant evaluation of new service features and the maintenance of a flexible infrastructure capable of absorbing the next wave of technological innovation. The history of this transition showed that the most successful implementations were those that viewed communication not as a utility, but as a strategic asset for global connectivity.