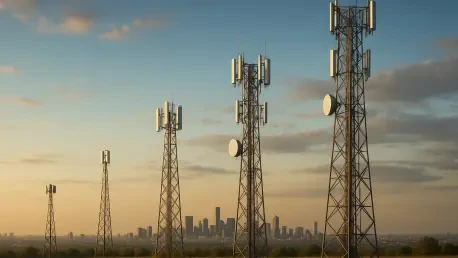
Specialized transmission technologies like radio frequency and microwave systems provide essential connectivity in industrial and remote settings where physical wiring is cost-prohibitive. This technological shift represents a broader movement in the global wireless communication sector, which is currently valued at approximately $274.76 billion. As the global economy transitions through 2026 and toward 2030, the reliance on these non-mainstream transmission mechanisms is expected to intensify, pushing the market valuation toward a projected $345 billion. The current landscape is defined by the integration of sophisticated systems that support enterprise mobility and the sheer volume of mobile data produced by billions of devices daily. Unlike traditional cellular networks, these specialized channels offer the flexibility and scalability required for complex industrial environments and scientific research. By removing the constraints of physical infrastructure, businesses can now implement real-time data monitoring and multimedia transfer in locations that were previously inaccessible, marking a definitive evolution in digital strategy and connectivity.
Infrastructure and the Demand for High-Speed Connectivity
The primary driver behind this rapid expansion is the relentless global demand for high-speed internet access. Consumers and corporations no longer view high bandwidth as a luxury but as a fundamental utility necessary for daily operations. This demand is fueled by the proliferation of bandwidth-intensive activities such as 8K video streaming, high-fidelity online gaming, and expansive cloud-based computing architectures. As remote and hybrid work models become permanent fixtures of the global economy, the necessity for reliable, high-capacity wireless connections has reached a critical peak. These systems must handle massive data loads without sacrificing speed or reliability, ensuring that productivity remains high regardless of a physical location. Consequently, the industry is seeing a surge in investment toward radio frequency and microwave solutions that can augment existing 5G and fiber-optic backbones, providing the necessary throughput for an increasingly digital society that depends on constant, seamless data availability across the planet.
Simultaneously, aggressive government-led initiatives to modernize digital infrastructure are providing a significant tailwind for the wireless sector. In many developed nations, the focus has shifted toward achieving universal gigabit-capable broadband coverage to ensure economic competitiveness. While fiber-optic cables form the core of these networks, wireless technology is often the only viable solution for the last mile of connectivity in challenging terrains or densely packed urban centers. These national projects create a robust foundation for further technological innovation by establishing high-speed backbones that wireless providers can leverage. Furthermore, the integration of these networks allows for greater redundancy and resilience in national communications systems, which is a key priority for modern digital governance. As these infrastructure projects mature between 2026 and 2030, the market for specialized wireless components is expected to grow as service providers strive to meet the stringent performance benchmarks set by regulatory bodies.
Emerging Technologies and Autonomous Systems
The rapid proliferation of the Internet of Things (IoT) serves as another major catalyst, requiring millions of low-power devices to maintain consistent communication over vast distances. Technologies like Low Power Wide Area Networks (LPWAN) and LoRaWAN protocols have become essential in this context, as they allow sensors and industrial monitors to operate for several years on a single battery while transmitting data across several miles. This efficiency is vital for sectors such as agriculture, where moisture sensors and livestock trackers must function in remote fields without manual intervention. Beyond simple monitoring, the rise of autonomous systems is placing new demands on wireless precision. Delivery drones, self-driving industrial vehicles, and automated warehouse robotics all rely on ultra-precise, real-time data transfers to navigate complex environments safely. These applications require the ultra-low latency provided by advanced radio frequency systems, ensuring that a split-second delay does not result in operational failure or safety hazards.
Innovation is also occurring in the orbital and architectural domains, where satellite-based internet and mesh networking are redefining connectivity boundaries. The expansion of low-Earth orbit satellite constellations is bringing high-speed access to rural and underserved regions that traditional terrestrial providers have long ignored. This democratization of data ensures that remote industrial sites, such as mining operations and offshore oil rigs, can integrate with global enterprise systems in real time. Meanwhile, the adoption of mesh network architectures and cognitive radio technology is maximizing spectrum efficiency. Cognitive radio systems can automatically detect available wireless channels and adjust transmission parameters on the fly, allowing for more dense user environments without the typical interference associated with high-traffic areas. These advancements represent a shift toward smarter, more adaptive communication systems that can self-heal and optimize performance based on current network conditions as more devices connect.
Regional Dominance and the Strategic Future
Geographically, the Asia-Pacific region maintains a commanding lead in the wireless communication market, driven by a combination of rapid urbanization and a massive electronics manufacturing infrastructure. Countries like China, Japan, and South Korea have positioned themselves as early adopters of next-generation wireless technologies, integrating them into everything from smart city projects to advanced factory automation. This regional dominance is supported by aggressive government policies that prioritize national digitization and provide subsidies for the development of local wireless hardware and software ecosystems. As we move from 2026 toward the end of the decade, Asia-Pacific is projected to remain the fastest-growing market, largely due to the increasing middle-class demand for mobile services in India and Southeast Asia. The concentration of major technology manufacturers in this region ensures a steady supply of innovative components, further solidifying its role as the global hub for wireless communication development through high-scale pilot programs.
Looking toward the future, the industry transitioned into a phase where the focus shifted from simple connectivity to the delivery of highly specialized, ultra-reliable low-latency communication (URLLC). This evolution was necessary to support high-stakes applications such as remote robotic surgery and smart grid management, where even a millisecond of lag could have catastrophic consequences. Industry stakeholders took proactive steps to ensure that spectrum management became more dynamic, allowing for the seamless integration of satellite, terrestrial, and specialized radio networks. The successful organizations prioritized interoperability and security, recognizing that a fully unplugged world required a foundation of trust and technical consistency. For businesses that capitalized on this $345 billion opportunity, the primary focus rested on developing energy-efficient hardware and scalable software protocols that adapted to the diverse needs of global clients. By emphasizing spectrum efficiency and low-power designs, the sector established a sustainable path for growth that redefined the global digital landscape.