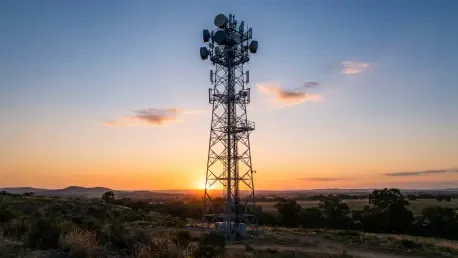
The upcoming release of approximately 800 megahertz of new mobile spectrum is expected to serve as a significant catalyst for leasing activity among major wireless infrastructure providers. This massive bandwidth expansion allows carriers to drastically improve their service quality, shifting the focus from broad 5G coverage to the intensive capacity required by modern mobile users. As the essential landlords of the cellular world, American Tower, Crown Castle, and SBA Communications represent the primary beneficiaries of this technological evolution. These Real Estate Investment Trusts control the physical tower space and specialized infrastructure that underpin nearly all wireless communications. While the industry is currently managing a transitional phase marked by tenant consolidation and interest rate shifts, the core demand for data continues to increase exponentially. This creates a market environment where infrastructure owners hold a critical position as gatekeepers of connectivity. Consequently, these companies find themselves at a vital junction of operational stability and long-term expansion.
Analyzing the Market Leaders and Growth Drivers
Diversification and Global Scale: The American Tower Strategy
American Tower stands at the forefront of the global infrastructure market, operating a massive network of over 148,000 sites that spans five continents. The company has distinguished itself from competitors by aggressively diversifying into the data center industry, most notably through its strategic acquisition of CoreSite. This expansion has successfully created a high-growth vertical that complements its traditional tower leasing, with data center revenue currently growing at double-digit rates. By integrating these two essential components of the digital economy, the firm provides a more comprehensive service to its tenants while stabilizing its own cash flows. Internationally, the company is capitalizing on the rapid development of mobile networks in Africa and the Asia-Pacific region, where the demand for modern connectivity is outstripping existing supply. This global reach ensures that the company remains resilient against localized economic fluctuations in any single market.
Data Center Integration: Expanding Beyond Traditional Towers
From a financial standpoint, the organization maintains a balanced profile that highlights its operational strength and disciplined capital management. It currently offers a dividend yield of approximately 3.79%, supported by a conservative payout ratio that remains under 65% of its adjusted funds from operations. This level of dividend safety is a key differentiator, especially when combined with the lowest leverage ratio among its peer group. Management has identified the current fiscal year as a stabilization period, or a trough, as it works through the remaining churn from previous carrier mergers. However, the long-term growth outlook remains robust, with expectations for mid-to-high single-digit revenue increases as the network capacity phase matures. By prioritizing balance sheet health and strategic diversification, the company offers a reliable pathway for investors who seek a blend of steady income and international growth potential within the infrastructure sector.
Domestic Pure-Play Strategy: Assessing Crown Castle Operations
Crown Castle has recently completed a significant transformation into a pure-play U.S. infrastructure operator, focusing its entire portfolio on the domestic market. This move was solidified by the sale of its fiber and small cell business for approximately $8.4 billion, a transaction that allowed the company to streamline its operations and return to its core tower leasing roots. Managing roughly 40,000 towers exclusively within the United States, the company is now a direct play on the capital expenditures of the major American carriers. This focus allows for simplified management and a concentrated bet on the world’s most advanced wireless market. However, such a strategy also increases the firm’s sensitivity to the specific spending patterns and regulatory changes occurring within the American telecommunications landscape. By shedding its non-core assets, the company has redirected its focus toward optimizing its existing tower footprint to meet the rising demand for domestic 5G.
Dividend Yield and Risk: Evaluating Crown Castle Payouts
The primary attraction for many investors in this domestic-focused REIT is its generous dividend yield, which currently hovers near the 5% mark. While this represents a significant source of immediate income, it comes with a higher risk profile due to a payout ratio that exceeds 92% of adjusted funds from operations. This narrow margin leaves the company with limited excess cash for expansion and makes it vulnerable to any unexpected decreases in leasing revenue. The firm is currently navigating the financial impact of lease expirations from DISH Network, which are projected to create a noticeable drag on total billings throughout the coming year. To counter these headwinds, the company is focused on aggressive debt reduction and a share buyback program funded by its recent asset sales. For investors who are primarily focused on high current yield, the stock offers a compelling but volatile option that requires close monitoring of domestic carrier consolidation and tenant financial health.
Assessing Long-Term Stability and Sector Trends
Financial Discipline and Yield Growth: The SBA Communications Model
SBA Communications employs a highly conservative financial strategy that sets it apart as a safety-first option within the wireless infrastructure sector. While it offers the lowest dividend yield among its peers, it boasts the most sustainable payout ratio at only 41% of its adjusted funds from operations. This low payout allows the company to retain a significant portion of its earnings to fund internal growth initiatives and aggressive dividend increases, which have led the industry over the past several years. By maintaining such a deep cushion, the firm is well-positioned to weather any temporary downturns in leasing activity without jeopardizing its returns to shareholders. Additionally, the company maintains a robust international presence, particularly in developing markets where the transition from 4G to 5G is still in its early stages. This provides a predictable long-term growth runway as international carriers modernize their networks to support increasing data usage.
Strategic Growth: International Connectivity and SBA Market Position
The company recently enhanced its financial standing by achieving an investment-grade credit rating, which allows it to access the bond markets at more favorable rates. This improvement in the cost of capital is essential for continuing its strategy of site acquisition and infrastructure optimization. While the company faces the same domestic churn challenges as its competitors due to carrier mergers, its low-leverage approach provides a higher degree of stability. The management team has focused on upgrading existing towers to accommodate the heavier equipment configurations required for 5G, which often results in higher rental income per site. Although foreign currency fluctuations introduce some volatility to its international earnings, the underlying business of providing essential tower space remains extremely resilient. For conservative investors who prioritize dividend safety and long-term compounding of value, the company represents a disciplined play on the continued expansion of global connectivity.
Industry Consolidation: Navigating the Impact of Carrier Mergers
A broader look at the industry reveals that the shift from initial 5G coverage to full-scale capacity enhancement is the primary driver of future leasing demand. Industry experts anticipate that network capacity requirements will need to double by 2030 to keep pace with the surge in mobile data usage driven by video streaming and industrial internet applications. This trend necessitates that carriers install more equipment on existing towers, leading to increased rental payments for infrastructure owners. However, the sector must first move past the hangover of previous carrier mergers, which has led to some redundancy and temporary tenant losses. Despite these short-term challenges, the long-term outlook remains overwhelmingly positive as the global economy becomes more reliant on high-speed wireless networks. The impending auctions of additional spectrum will further accelerate this growth, as carriers scramble to deploy new frequencies and maintain their competitive edge.
Strategic Insights for the Future: Actionable Infrastructure Trends
The investigation into the wireless infrastructure sector indicated that the fundamental business of tower leasing remained one of the most stable investments in the digital economy. While the market faced temporary challenges from carrier consolidation and shifting interest rates, the overarching demand for network capacity continued to provide a reliable growth engine. Strategic investors identified that the choice between these major REITs depended on a specific balance of risk, geographic focus, and yield requirements. Those seeking safety prioritized low payout ratios and international growth runways, while income-oriented participants focused on domestic pure-plays with high immediate yields. Ultimately, the industry moved toward a more mature phase where balance sheet discipline and technical optimization became the primary drivers of shareholder value. The period of rapid tower construction gave way to a focus on density and data center integration, ensuring that these infrastructure giants remained the vital gatekeepers of the global connectivity landscape.