Vladislav Zaimov has spent years navigating the labyrinth of enterprise connectivity, specifically focusing on how mission-critical environments handle the surge of data demands. As a seasoned expert in telecommunications and risk management, Zaimov has a front-row seat to the transformation of infrastructure within vulnerable and high-stakes networks. Today, we delve into the recent, massive deployment of a private 5G network at Minneapolis-St. Paul International Airport, a project that serves as a blueprint for the “smart cities” of the future. Our discussion covers the strategic implementation of the CBRS spectrum, the shifting rivalry between global vendors like Ericsson and Nokia, and the operational shifts occurring as major industries move beyond the limitations of traditional Wi-Fi. We explore why predictable connectivity has become the gold standard for modern logistics and how the competitive landscape for 5G hardware is being reshaped by specialized niche players.
Managing a private network across five square miles of complex airport terrain presents unique infrastructure challenges. How did the collaboration between the Metropolitan Airports Commission and the technical teams address the “miniature city” requirements of MSP, from public safety to the coordination of parking facilities?
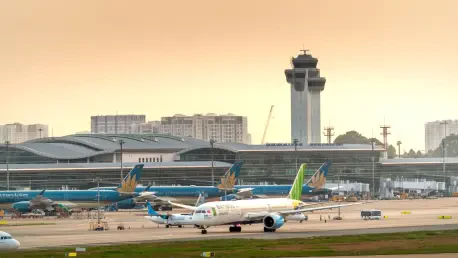
The sheer scale of an environment like Minneapolis-St. Paul International Airport is staggering when you realize it functions almost exactly like a self-contained municipality. We aren’t just talking about a couple of gates; this deployment covers five square miles of terrain that is constantly in motion, requiring its own dedicated public safety, maintenance, and security protocols. To pull this off, the team worked closely with Insight Enterprises and the Metropolitan Airports Commission (MAC) to ensure the backbone of the network could handle what we call “enterprise-grade firepower.” This wasn’t just about sticking a few routers in a hallway; it was about building a secure digital platform that could blanket both indoor terminals and outdoor airfields with the same level of reliability. You can feel the complexity of the operation when you look at the dozens of airport vehicles now equipped with Cradlepoint routers, which allow ground crews to access operational applications in real-time while navigating the tarmac. By treating the airport as a miniature city, the infrastructure was designed to be robust enough for secure video transmissions and the high-stakes coordination of parking and maintenance facilities that never sleep.
We often hear that traditional Wi-Fi has reached its limits in industrial settings where reliability is non-negotiable. In the context of the MSP deployment, what were the specific operational pain points where Wi-Fi couldn’t keep up, and how did private 5G fill that gap?
In an environment as dense and metallic as an airport, Wi-Fi often struggles with interference and “dead zones” that can be catastrophic for critical operations. At MSP, the decision-makers realized that for use cases like Axis Communications’ private cellular-enabled camera systems, Wi-Fi simply wasn’t cutting it. When you have high-definition video monitoring running on airport trams that are moving through different zones, any drop in connectivity is a security risk. Private 5G provides what we call “predictable connectivity,” meaning the latency and throughput are guaranteed, which is paramount for secure video and connected vehicle operations. In manufacturing, seaports, and warehouses, we are seeing the same trend where the “best effort” nature of Wi-Fi fails to meet the needs of HD monitoring and real-time data flow. By shifting to a private cellular network, the airport ensured that their trams and vehicles maintain a rock-solid link to the command center, providing the kind of reliability that allows for true digital transformation.
The Citizens Broadband Radio Service (CBRS) is a uniquely American approach to spectrum management. How does this three-pronged tiered system, sitting at the 3.5-3.7 GHz band, provide a competitive advantage for enterprises while still protecting incumbent users like the Navy?
CBRS is essentially the “Swiss Army knife” of spectrum in the United States, sitting smack dab in the middle of the 3 GHz band, which makes it incredibly versatile for private deployments. It’s a shared system that carefully balances the needs of different users, using a three-tiered priority structure to ensure that critical incumbent users, such as the U.S. Navy, aren’t interrupted. For a place like MSP, using CBRS allows them to own and operate their network without the massive overhead or red tape often associated with licensed bands. However, there is a lot of tension in the industry right now, with major carriers like AT&T lobbying the federal government to move the CBRS band to make room for full-power licensed uses. Despite this political maneuvering, CBRS remains the primary vehicle for private 5G because it offers that “sweet spot” of range and capacity. It provides the stability of a private network while being flexible enough to be deployed in a “click-to-deploy” fashion, which is exactly how Ericsson is scaling these solutions for airports and smart factories.
With Nokia signaling a potential retreat from its Enterprise Campus Edge unit, there seems to be a significant opening in the market. How is the competitive landscape shifting, and is Ericsson effectively picking up the slack in sectors like aviation and manufacturing?
The dynamics between the major vendors are shifting quite rapidly, and it’s a fascinating time to watch the market evolve. Currently, Nokia holds a significant lead, accounting for about 28% of global private cellular RAN sales and 22% of core sales, but Ericsson is breathing down their neck. As Nokia contemplates selling off units that target smaller campus-wide networks to focus on mission-critical areas like defense and utilities, Ericsson is moving aggressively to capture that territory. We are seeing Ericsson win deals in verticals that were previously Nokia strongholds, such as warehousing and aviation, by working much closer with system integrators like Future Technologies Venture. Research suggests that the Swedish vendor might even overtake Nokia within the next twelve months, although the margin will likely be slim. This rivalry is driving a lot of innovation, as both companies realize that private 5G is not an “impulsive buy” for a customer; it requires a bulletproof use case and a high degree of trust in the vendor’s long-term roadmap.
The shift at Ericsson’s own smart factory in Lewisville, where they moved from CBRS to a licensed C-band private network, suggests an evolving strategy. What does this tell us about the maturity of the device ecosystem and the long-term scalability of private networks compared to their initial 2021 case studies?
The Lewisville factory is a perfect example of how a connectivity strategy must evolve alongside the technology. Back in 2021, CBRS was the primary tool for proving the efficiency and environmental benefits of a private network, but as use cases scale, the requirements often change. The facility manager noted that they transitioned to a licensed 5G C-band network because it allowed them to better evaluate the maturity of the device ecosystem. When you are running a high-output smart factory, you need to know that every single sensor, robot, and handheld device can communicate seamlessly, and sometimes a licensed spectrum provided by a mobile operator offers a more streamlined path for that specific hardware. It doesn’t mean CBRS is failing; rather, it shows that enterprises are becoming more sophisticated in how they match their spectrum choice to their operational needs. This evolution highlights a broader trend: the industry is moving past the “experimental” phase of 2021 and into a mature era where the focus is on scaling and long-term stability.
As we see specialized vendors like Celona, Druid Software, and Airspan gaining traction with multi-site deployments for giants like Nestlé and Google, what is your forecast for the private 5G market?
We are finally entering the “take-off” phase for the private 5G market, and I expect to see a surge of specialist vendors making life very difficult for the traditional giants. While Nokia and Ericsson are the big names outside of China—where Huawei remains the leader—there is a long list of agile players like Celona, JMA Wireless, and HPE that are winning significant contracts with global brands like Cargill and BP. My forecast is that we will see a move away from “one-size-fits-all” solutions toward highly customized, multi-site deployments where specialized RAN and core vendors offer a level of flexibility that the big players struggle to match. In the coming years, the success of private 5G will be defined by its ability to integrate into existing industrial workflows, moving from a “cool technology” to a mandatory piece of infrastructure. For the wireless industry, which has seen its fair share of disappointments, this specific sector is proving to be the real engine of growth, and I expect the total number of private 5G customers to continue climbing into the thousands as the “click to deploy” model becomes the global standard.