The Turning Tide for China’s Connectivity Leaders
The recent financial turbulence shaking the foundations of China’s state-owned telecommunications sector serves as a chilling bellwether for the health of the world’s second-largest economy. Third-quarter results for industry giants have triggered widespread concern as the era of rapid expansion meets a cooling domestic market. For China Mobile and China Telecom, a massive user base has proved to be a hollow shield against the combined weight of increased taxation and weakening consumer demand.
Market observers note that this downturn is not a mere seasonal fluctuation but a fundamental shift in the landscape. As the backbone of digital modernization, these firms must navigate a path where state fiscal changes clash with a less affluent public. Understanding these fractures is vital for anyone tracking the stability of the regional market, as the ripple effects extend far beyond subscriptions into the infrastructure of the digital age.
Analyzing the Fractures in the State-Owned Telecom Model
The Revenue Erosion Caused by Soft Demand and Fiscal Shifts
Economic analysts highlight a dual-threat environment where a significant tax hike implemented earlier this year has coincided with a contraction in household spending. China Mobile saw its quarterly earnings drop by 12.5%, a figure that underscores how sheer volume no longer offsets the rising costs of doing business under aggressive fiscal policy.
As consumers tighten their belts, the revenue per user is failing to keep pace with the operational expenditures required to maintain massive networks. This shift suggests that size no longer guarantees profitability when the environment turns hostile, leaving state-backed titans vulnerable to sudden margin compression.
Stagnation in Traditional Services and the Cloud Dilemma
Legacy services have reached a point of terminal stagnation, forcing a risky pivot toward AI and cloud computing. While firms have poured billions into these initiatives, industry experts point out that these emerging sectors currently lack the scale to compensate for the decay in traditional revenue.
The capital expenditure required for AI development places a strain on balance sheets already weakened by declining profits. Betting on a corporate sector that is itself facing a slowdown creates a dangerous cycle of investment without immediate returns. This transition period leaves the giants caught between a shrinking past and an unproven future.
Infrastructure Fragility and the China Tower Warning Sign
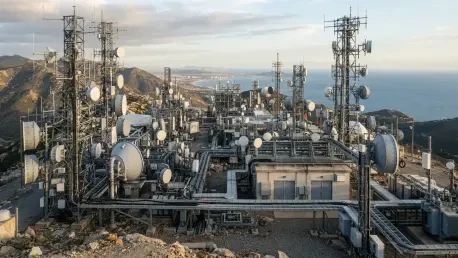
The 12% decline in EBITDA for China Tower signals systemic cooling within the infrastructure layer. Typically viewed as a stable asset, the decline in tower sales indicates that service providers are scaling back their own expansion plans to preserve cash in an uncertain climate.
The underutilization of physical hardware points to a strategic retreat by major operators who are now prioritizing efficiency over growth. This fragility in the physical layer serves as a warning that economic pressures are now penetrating every structural level of the telecommunications industry.
Investor Skepticism and the Identity Crisis of Tech-Service Firms
Telecom executives are rebranding their organizations as “technology services enterprises” to regain market favor, but share prices continue to slide. Financial consultants argue that the market remains skeptical of the ability to transform rigid bureaucracies into agile technology innovators during a broad economic slowdown.
Investors doubt that a mere label change can fix the fundamental problem of squeezed margins. Without a clear path to high-margin growth that avoids saturated consumer markets, this strategic pivot remains a difficult sell for those looking for long-term stability and growth.
Navigating a High-Stakes Financial Transition
Leadership must focus on extracting higher value from existing 5G infrastructure through specialized enterprise applications. Instead of chasing raw subscriber numbers, the focus should shift toward operational efficiency to counter the impact of new tax burdens. Firms that successfully integrate AI-driven analytics will be better positioned to weather the storm without overextending their balance sheets.
Stakeholders should look for companies demonstrating a disciplined approach to expenditure and a clear strategy for diversifying revenue. High-margin cloud services and industrial solutions offer the best path forward if managed for profitability rather than market share. Adopting a lean, value-driven model will be essential in an environment where effortless expansion is no longer an option.
Sustaining Resilience in a Cooling Economic Climate
The industry recognized that the confluence of tax adjustments and tepid spending necessitated a total reimagining of the state-owned business model. Decision-makers shifted their focus toward sustainable margins, favoring niche technological integrations over the pursuit of sheer subscriber volume. This transition period highlighted the importance of fiscal agility, as companies that streamlined their internal processes managed to offset the impact of the tax hike effectively. Moving forward, the successful players prioritized the development of high-margin AI and enterprise cloud services to stabilize their long-term revenue. These strategic pivots provided the necessary foundation for resilience, ensuring that the digital backbone of the nation could survive a fundamentally altered economic landscape.