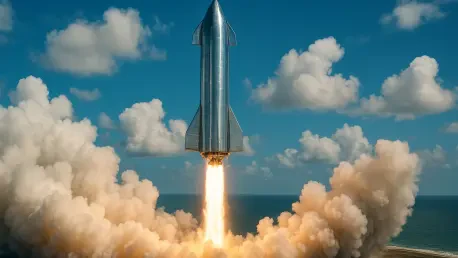
A vacuum engine failure during the fourteenth test flight resulted in an early splashdown near Chile, highlighting the technical hurdles that remain despite the mission’s orbital success. This mission, launched from the Starbase facility in Texas, represents a transformative moment where the platform transitioned from a purely experimental prototype to a functional heavy-lift vehicle capable of delivering payloads. By successfully deploying 26 Starlink V3 satellites into their designated orbits, the company demonstrated that its most ambitious project is finally ready to bolster the global internet constellation. This achievement serves as a vital proof of concept for the massive craft, which is engineered to handle far more complex tasks than any preceding rocket. While the premature splashdown prevented the intended multiple Earth orbits, the core objective of orbital insertion was met with precision. This progress suggests that the era of rapid satellite deployment is no longer a distant vision but a tangible reality that will redefine how the industry views orbital logistics and planetary exploration.
Scaling the Infrastructure: The Starlink V3 Advantage
The strategic pivot toward the Starlink V3 architecture is fundamental to understanding why the Starship platform is so critical for the current financial trajectory of the enterprise. Each Starship launch is designed to carry approximately 60 of these next-generation satellites, a figure that dwarfs the capacity of the Falcon 9 by nearly twentyfold when considering total mass and volume. Beyond sheer numbers, the V3 units represent a significant technological leap, offering approximately ten times the operational capability of their predecessors. This exponential increase in bandwidth and processing power is necessary to meet the rising global demand for low-latency internet services. By utilizing the massive internal volume of the rocket, the company can deploy entire orbital shells with fewer launches, drastically reducing the cost per bit transmitted. This efficiency is the primary engine behind the company’s recent performance, where the connectivity segment has emerged as the sole profitable division for the entire corporation.
Looking closely at the financial data, the impact of these technological advancements becomes even more apparent in the context of the recent quarterly performance figures. In Q2, the connectivity division generated a staggering $4.3 billion in revenue, which fueled a 92% year-over-year surge for the entire organization. This momentum has led management to set an incredibly ambitious target of $100 billion in annualized revenue by the end of this year, a goal that relies heavily on the continued success of the Starship program. The ability to launch hardware at this scale is not just about vanity; it is about establishing a dominant market position that competitors find nearly impossible to challenge. As the fleet grows toward the envisioned 11,000-satellite constellation, the barrier to entry for rivals becomes increasingly steep. Maintaining this growth rate requires a seamless integration of the new heavy-lift capabilities into the existing launch schedule, ensuring that every flight contributes directly to the bottom line.
Navigating Market Volatility: Investor Expectations
Despite the undeniable technical progress seen during the fourteenth flight, the market reaction has been characterized by a cautious “show-me” attitude among institutional investors. The stock, currently trading under the ticker $SPCX, has experienced a 10% decline over the past month, landing at approximately $145. This price point sits significantly below the 52-week high of $226, reflecting concerns about the timing of full operational status. Nevertheless, many analysts remain bullish, maintaining a price target of $224 based on the company’s massive $2 trillion valuation. This confidence stems from the organization’s overwhelming dominance in the satellite market, where it currently operates thousands of active units compared to fewer than 700 for its nearest competitor. The sheer scale of this infrastructure provides a moat that few other private entities can hope to replicate. Investors are essentially betting on the long-term utility of a fully reusable launch system that can lower the cost of access to space by orders of magnitude.
However, the path to achieving a $224 price target is fraught with engineering complexities and the historical tendency of leadership to set overly aggressive timelines. The failure of the vacuum engine during the latest mission serves as a stark reminder that while orbital insertion is possible, perfecting the return and reuse of the vehicle is another matter entirely. The ultimate key to long-term profitability lies in the ability to land the Super Heavy booster and the Starship itself for rapid refurbishment. Without full reusability, the economics of the program cannot fully realize the projected margins that support such a high valuation. Market participants are now focused on whether the company can move beyond successful test flights toward a standardized, high-frequency launch cadence. The transition from a development-focused culture to one centered on industrial reliability is perhaps the greatest challenge facing the team today. Until the company can prove that these massive ships can fly multiple times with minimal maintenance, the stock may remain volatile.
Bridging the Gap: Global Connectivity Goals
Achieving a truly seamless global network requires more than just successful launches; it requires reaching a critical mass of V3 satellites in orbit. Internal projections suggest that the company needs approximately 1,000 of these advanced units deployed before consumers experience the substantial boost in speed and reliability that was promised. This milestone is currently expected to be reached around Q2 of next year, assuming the launch frequency continues to accelerate as planned. The integration of these satellites will allow the network to handle significantly more traffic in densely populated areas, expanding the addressable market from rural users to urban professional segments. This shift is vital for capturing the higher-margin corporate and government contracts that will drive the next phase of revenue growth. As the network matures, the focus will likely move from raw deployment to optimizing the handover protocols and ground station infrastructure. These incremental improvements are what will ultimately turn the technical success of Starship into a commercial victory.
The orbital achievement of the fourteenth flight provided the necessary evidence that the Starship architecture was capable of fulfilling its primary role as a heavy-lift workhorse. Stakeholders recognized that the successful deployment of the V3 payload outweighed the setbacks of the engine failure, signaling a shift in the company’s operational priorities. To capitalize on this progress, analysts recommended that observers use sophisticated tools like the TIKR Valuation Model to evaluate future growth forecasts against the inherent risks of space flight. The organization focused on stabilizing its launch cadence and perfecting the reusability cycle, which remained the final hurdle for achieving its ambitious financial targets. By moving toward a model of consistent execution, the company sought to bridge the gap between its current valuation and the massive potential of its orbital infrastructure. Ultimately, the lessons learned from the splashdown near Chile were used to refine the hardware for upcoming missions, ensuring that the next phase of satellite deployment remained on schedule.