The South African telecommunications market stands on the precipice of its most significant transformation in decades as industry leaders weigh the consequences of a massive corporate merger. The inclusion of Telkom’s enterprise arm, BCX, would immediately strengthen MTN’s ability to compete for high-value contracts within the South African government and corporate sectors. This official entry into preliminary discussions to acquire the entire issued share capital of Telkom SA marks a tectonic shift in the regional digital landscape. By late 2026, the potential merger has become the central focus of market analysts, as it aims to consolidate Telkom’s extensive mobile subscriber base and industry-leading fiber assets under the MTN umbrella. If the transaction is successfully finalized, it would create the largest telecommunications operator in South Africa by total subscriber volume, effectively dethroning Vodacom from its long-held top position. The proposal remains in an early stage, but MTN has expressed significant flexibility regarding the payment structure, offering options that include cash or MTN shares to satisfy Telkom’s diverse group of shareholders and stakeholders.
The Strategic Logic: Consolidating a Fragmented Market
MTN Group CEO Ralph Mupita has consistently championed the “consolidation thesis” as a necessary evolution for the telecommunications industry in emerging markets. He argues that the current environment, characterized by multiple medium-sized players, suffers from fragmented returns that prevent any single entity from making the massive, sustained infrastructure investments needed for the coming decade. By merging these operations, Mupita believes the industry can move away from a model of duplicated towers and fiber lines toward a more integrated, efficient system. This approach would allow the combined entity to focus its capital on next-generation 5G rollout and high-speed broadband expansion rather than competing for the same limited pool of urban subscribers. The objective is to create a more stable market where significant cash flow can be redirected toward technological breakthroughs that benefit the entire digital economy, rather than being thinned out across redundant operational costs.
Furthermore, MTN has explicitly stated its preference for acquiring existing infrastructure over building its own independent fiber network from the ground up in saturated urban zones. Because Telkom already possesses extensive “in-the-ground” assets through its legacy and modern developments, this acquisition serves as a strategic shortcut to national market dominance. This method allows MTN to bypass years of disruptive construction and the massive capital expenditure typically associated with greenfield projects. In an era where speed to market is critical for the adoption of cloud services and edge computing, gaining immediate access to high-value assets is essential for maintaining a competitive edge. This vision aligns with global trends where established carriers prioritize asset acquisition to fortify their balance sheets against the rising influence of international tech giants. By securing these physical networks now, MTN ensures it remains the primary gateway for all South African digital traffic.
Infrastructure Dominance: Leveraging Openserve and Fiber Assets
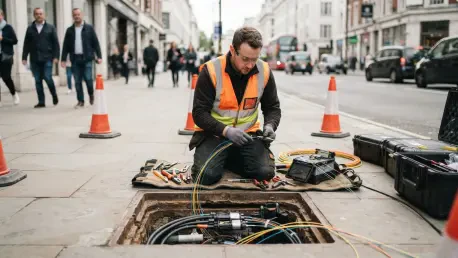
While the mobile subscriber base is a vital component of the deal, the true centerpiece of the acquisition is Openserve, Telkom’s wholesale and fiber division. Openserve is widely considered the most critical piece of digital infrastructure in South Africa, providing the backbone for much of the country’s high-speed connectivity. For MTN, securing this division means gaining control over the essential “backhaul” that connects mobile towers to core networks, a service upon which many of its competitors currently rely. The financial health of this segment is robust, with significant growth reported in fiber-to-the-home and fiber-to-the-business sectors. By integrating these assets, MTN can significantly lower its own operational costs while simultaneously generating a steady stream of wholesale revenue from other internet service providers. This dual advantage positions the company not just as a retail provider, but as the foundational utility provider for the entire South African telecommunications sector.
Beyond the physical fiber lines, the integration of BCX provides MTN with a specialized entry point into the lucrative world of managed information and communications technology services. BCX has long been a leader in providing complex digital solutions for corporate and government clients, ranging from data center management to cybersecurity and cloud integration. Historically, MTN has focused primarily on mobile connectivity, but this acquisition would facilitate a rapid transition into a comprehensive technology provider. By combining MTN’s global reach and mobile expertise with the local enterprise depth of BCX, the new entity could offer end-to-end digital transformation packages. This strategy is essential for capturing the next wave of corporate spending as businesses migrate their legacy systems to the cloud. The ability to provide both the connectivity and the underlying service layer creates a powerful value proposition that would be difficult for any regional competitor to match.
Financial Valuation: Assessing Total Enterprise Worth
Market analysts have begun modeling potential offer prices based on Telkom’s market capitalization and share price performance leading up to the official confirmation. While a formal price has not been publicly disclosed, estimates suggest that any successful bid would need to include a significant premium to satisfy private shareholders and the South African government, which remains a key stakeholder. Depending on whether the premium is set at 20% or 30% above the current trading value, the equity purchase price could reach upward of R41 billion. This reflects the high strategic stakes involved and the recognition of Telkom’s intrinsic value, which many believe has been underpriced by the market in recent years. The negotiation process is expected to be rigorous, as Telkom’s board will need to justify the long-term benefits of the merger compared to their independent turnaround strategy, which has shown signs of success in the fiber and mobile divisions.
When factoring in Telkom’s existing net debt, the total enterprise value of the transaction is estimated to fall between R44.4 billion and R47.6 billion. These staggering figures highlight the scale of the financial commitment MTN is prepared to make to secure its future dominance. Such a massive investment requires a clear path to profitability, which MTN intends to achieve through significant synergy savings and the monetization of Telkom’s extensive property and tower portfolio. The financial architecture of the deal, whether it involves a heavy cash component or a share-swap arrangement, will have long-term implications for MTN’s leverage and its ability to continue dividend payments. Investors are watching closely to see how the company balances its ambitious growth goals with the need for fiscal discipline in a volatile global economy. The successful execution of this valuation would represent one of the largest and most complex deals in the history of the South African stock exchange.
Regulatory Barriers: Navigating Complex Competition Laws
The path to finalizing this merger is expected to be fraught with challenges from South Africa’s competition authorities, which have historically maintained a skeptical view of industry consolidation. Regulators often fear that allowing a dominant operator to control a major fiber network creates an “unfair incentive” to disadvantage smaller rivals who depend on that infrastructure. A key concern is the potential for vertical integration, where the combined entity might prioritize its own retail services on the Openserve network while raising prices or lowering service quality for competing internet service providers. To overcome these hurdles, MTN will likely have to present a compelling case that the merger’s efficiencies, such as expanded rural coverage and improved service reliability, far outweigh the risks to competition. The precedent set by recently blocked deals in the sector suggests that the Competition Tribunal will demand extensive concessions before granting approval.
To satisfy these regulatory requirements, MTN may be forced to offer significant remedies that guarantee the continued neutrality of the Openserve network. These conditions could include long-term, fixed-price wholesale contracts for competitors and specific, legally binding investment commitments in underserved and rural regions of the country. Furthermore, the company may need to ensure that the BCX enterprise arm remains sufficiently separate to prevent anti-competitive practices in the corporate ICT market. Navigating this regulatory minefield requires a delicate balance of legal expertise and political negotiation, as the South African government has a vested interest in both the success of the telecommunications sector and the protection of consumer choice. If the merger fails to meet these strict criteria, it could face a lengthy appeals process or be blocked entirely, leaving both companies to rethink their long-term strategies in an increasingly crowded and competitive marketplace.
Market Outlook: Balancing Innovation and Connectivity
The proposed acquisition raised fundamental questions about whether a consolidated market structure actually benefited the South African public in the long run. Proponents argued that a strengthened MTN would have a more robust balance sheet to accelerate the rollout of high-speed fiber and 5G to remote areas that were previously neglected due to high infrastructure costs. By reducing the waste associated with building overlapping networks in wealthy urban areas, the industry could become more sustainable and technologically advanced, potentially leading to better overall network reliability for every citizen. The idea was that a national champion could better represent South African interests on the global stage, competing with international giants while ensuring that the domestic digital economy remained under local control. This perspective emphasized the importance of scale in an era where massive capital is required to keep pace with global technological shifts.
Building on this foundation, the proposed acquisition established a new framework for evaluating how traditional mobile carriers could successfully transition into diversified technology providers. As the discussions progressed throughout the year, the focus shifted from simple subscriber counts to the long-term viability of integrated digital ecosystems that combined fiber, mobile, and cloud services. Industry leaders recognized that the ultimate solution involved more than just consolidation; it required a commitment to maintaining open access for third-party providers to ensure that innovation did not stagnate under a duopoly. The realization that infrastructure sharing could coexist with intense service-level competition provided a blueprint for other emerging markets facing similar challenges. By the end of this period, the dialogue moved toward a national consensus that prioritized universal access and technological sovereignty, ensuring that the infrastructure of the future was built on a foundation of both corporate strength and public accountability.